Financial reporting is the process of preparing and presenting information about a business’s financial activities, position, and performance. It includes formal financial statements, explanatory notes, management commentary, and, depending on the organisation and jurisdiction, other disclosures.
The subject can sound like a technical exercise reserved for accountants. In practice, financial reporting is the shared reference point that helps owners, managers, lenders, investors, regulators, employees, and commercial partners understand what a business has, what it owes, how it performed, and how it generated or used cash.
That does not mean a financial report predicts the future or gives a business a single definitive value. The IFRS Conceptual Framework for Financial Reporting says general-purpose reporting is intended to provide useful information to existing and potential investors, lenders, and other creditors when they make decisions about providing resources to an entity. The report is evidence for decision-making, not a substitute for judgement.
What does financial reporting include?
Financial reporting normally begins with accounting records: invoices, receipts, payroll data, loan records, asset registers, bank transactions, and other evidence of economic activity. Those records are organised under an applicable reporting framework and summarised for a defined period.
The result may be an internal monthly management pack, annual accounts filed with a public authority, or a public company’s full annual report. The format changes with the audience, but the underlying purpose is similar: to communicate financial information consistently enough that another person can interpret and compare it.
Financial reporting is broader than bookkeeping. Bookkeeping records transactions. Financial reporting explains what those transactions mean when viewed together. It can show that revenue increased while cash declined, for example, because customers have not yet paid or because the business invested heavily in equipment. That context is where the reporting becomes useful.
The core financial statements
A complete set of statements is read as a connected picture rather than as four unrelated documents. The U.S. Securities and Exchange Commission’s beginner’s guide to financial statements identifies four principal statements.
1. Statement of financial position
Often called the balance sheet, this statement shows a business’s assets, liabilities, and equity at a particular date. Assets may include cash, inventory, equipment, property, receivables, and certain intangible assets. Liabilities include obligations such as loans, unpaid supplier invoices, taxes payable, and other amounts owed. Equity represents the owners’ residual interest after liabilities are considered.
The basic relationship is:
Assets = Liabilities + Equity
Because it is a snapshot, the statement of financial position does not explain every cash movement during the period. It does, however, help users consider liquidity, solvency, the composition of resources, and the claims against those resources.
2. Income statement
The income statement, also called a profit and loss statement, reports revenue, expenses, and the resulting profit or loss over a period. It helps readers assess operating performance, margins, cost patterns, and whether the business generated a surplus from its activities during that period.
Profit is not the same as cash received. Under accrual accounting, revenue and expenses may be recognised when earned or incurred rather than when money changes hands. A sale on credit can increase revenue before the customer pays; depreciation can reduce reported profit without being a current-period cash payment.
3. Cash flow statement
The cash flow statement explains how the cash balance changed between two reporting dates. It commonly separates cash flows from operating, investing, and financing activities.
- Operating activities: cash generated or used by the main business activities.
- Investing activities: cash spent on or received from long-term assets and investments.
- Financing activities: cash raised from or returned to lenders and owners.
This statement matters because a business can report a profit while facing a cash shortfall. It may need cash to pay wages, suppliers, tax, interest, and loan principal even when its income statement shows positive earnings.
4. Statement of changes in equity
This statement explains movements in owners’ equity during the period. Depending on the entity, changes may result from profit or loss, new capital, distributions, share transactions, or other recognised gains and losses.
Why financial reporting matters to businesses
It supports better decisions
Managers need more than sales totals to decide whether to hire, expand, reduce costs, change prices, buy equipment, or delay an investment. Financial reports connect those decisions to measurable results.
A useful management review might compare current revenue with the same period last year, examine gross margin by product, track overdue receivables, and test whether projected cash can cover upcoming commitments. The point is not to produce more figures for their own sake. It is to turn financial information into decisions that can be explained and revisited.
It makes access to finance more practical
Lenders and investors generally need evidence before committing capital. Financial statements give them a structured way to consider a business’s earnings, assets, debt, cash generation, and financial obligations.
The report will not remove uncertainty. It can reduce avoidable uncertainty by showing how the numbers were produced and by making assumptions and accounting policies visible. This is one reason the FASB’s conceptual framework describes financial reporting as information intended to support decisions about providing resources to an entity.
It creates accountability and continuity
Financial reporting preserves a record of how resources were obtained and used. That record is useful when ownership changes, a new finance team joins, a lender reviews the business, or directors compare actual results with an approved plan.
It also gives different groups a common basis for discussion. Sales may focus on bookings, operations on capacity, and finance on recognised revenue and cash collection. A well-prepared reporting process helps connect those views without pretending they are identical measures.
It supports compliance and transparency
Many businesses have legal, tax, contractual, or regulatory reporting obligations. The precise requirements depend on factors such as the entity’s legal form, size, public status, industry, and jurisdiction. Some organisations prepare accounts for filing; others also undergo an audit or independent review.
For readers who want a broader example of how published accounts function as a source of business information, the phrase financial reporting in professional services provides a neutral route to an industry-focused discussion. The general lesson is that published accounts are designed to communicate financial information to people who may not have access to the organisation’s internal records.
What makes financial information useful?
Numbers become more useful when their meaning and limitations are clear. The IFRS framework identifies relevance and faithful representation as fundamental qualities. In plain language, information should matter to a decision and should represent the underlying economic activity without deliberate distortion.
Other qualities improve usefulness:
- Comparability: readers can identify similarities and differences across periods or businesses.
- Verifiability: knowledgeable observers can reach reasonable agreement that the information represents what it claims to represent.
- Timeliness: the information arrives while it can still influence a decision.
- Understandability: the information is classified, presented, and explained clearly enough for an informed reader to use it.
These qualities involve trade-offs. A report that arrives months late may be carefully prepared but less useful for immediate decisions. A very detailed report may contain valuable information but become harder to navigate. Good reporting is not simply a matter of adding more pages.
Financial reporting is not the same as financial analysis
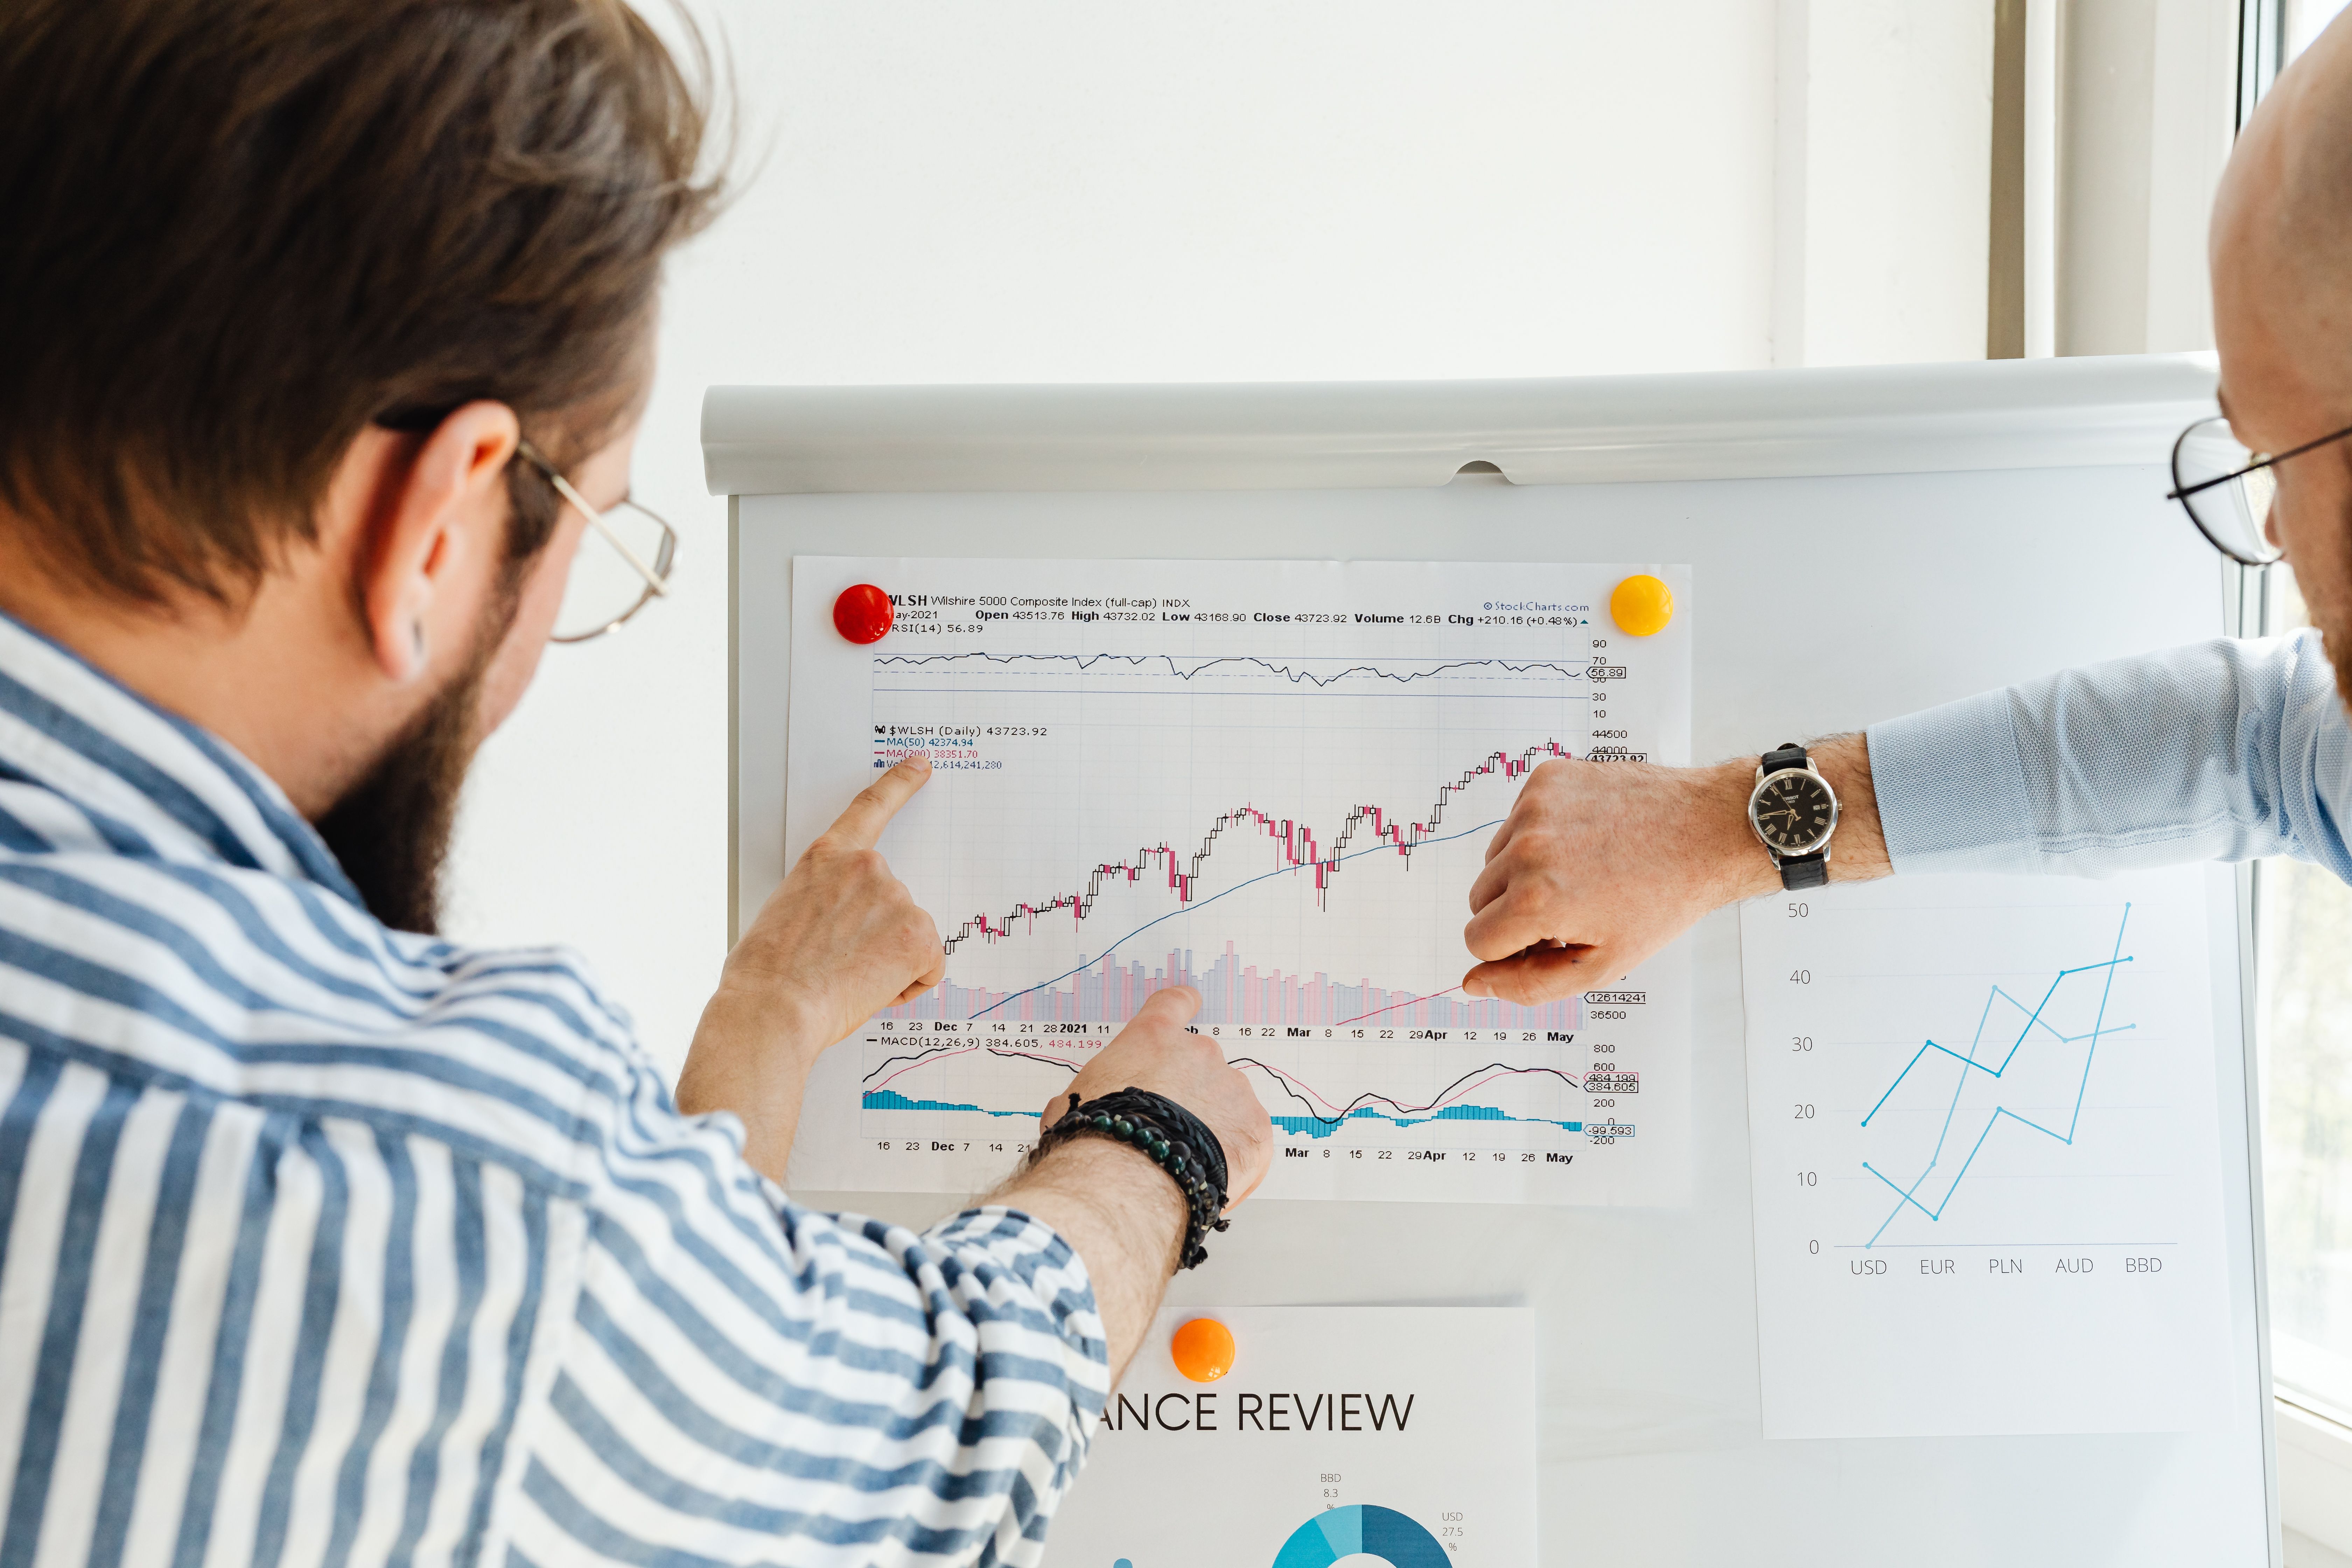
Financial reporting presents the underlying information. Financial analysis interprets it.
Analysis may include ratios, trend comparisons, budgets, forecasts, working-capital reviews, and scenario testing. For example, a reader could calculate a current ratio, compare operating cash flow with reported profit, or examine how much of the increase in revenue remains unpaid by customers.
The distinction matters because a report can be accurate without answering every business question. Financial statements show what has been reported under the relevant framework. Analysis adds questions about causes, relationships, and possible implications. Both are necessary for sound decision-making, but they should not be confused.
How to read a business’s financial reports
A practical review can follow this sequence:
- Start with the reporting period and basis. Check the dates, currency, accounting framework, and whether the figures are for one entity or a consolidated group.
- Read the income statement. Look beyond revenue to gross profit, operating expenses, finance costs, tax, and the pattern of profit or loss.
- Check the statement of financial position. Consider cash, receivables, inventory, debt, payables, and the relationship between current assets and current liabilities.
- Follow the cash. Compare cash generated from operations with investing needs and financing activity.
- Read the notes. Accounting policies, commitments, contingencies, related-party transactions, and significant estimates can change how the headline figures should be understood.
- Compare periods carefully. Investigate large movements rather than assuming that growth or decline has one obvious cause.
One statement rarely answers the whole question. Revenue growth may look encouraging until receivables and cash collection are reviewed. A healthy cash balance may look reassuring until upcoming debt repayments and capital commitments are considered. The strongest conclusions come from connections between the statements and the notes.
Common limitations to keep in mind
Financial reporting is important, but it is not a complete description of a business. Reports are historical or anchored to a reporting date, while decisions often concern the future. They also involve estimates, such as useful asset lives, expected credit losses, provisions, and the timing of revenue recognition.
Different businesses may use different measures or face different economic conditions, so direct comparisons require care. A general-purpose report is also not designed to contain every operational measure that management uses. Customer retention, product quality, staff capability, and market conditions may be important even when they do not appear as a single line in the primary statements.
The right response is not to dismiss the reports. It is to read them with context, understand the accounting basis, and combine them with other relevant information.
Frequently asked questions
What is the main purpose of financial reporting?
Its main purpose is to provide structured financial information that helps users assess a business’s financial position, performance, cash flows, resources, obligations, and prospects.
Who uses financial reports?
Owners, managers, investors, lenders, creditors, regulators, tax authorities, employees, and commercial partners may use them. The primary audience for general-purpose reporting is typically existing and potential investors, lenders, and other creditors.
What is the difference between accounting and financial reporting?
Accounting includes recording, classifying, measuring, and reviewing financial transactions. Financial reporting is the communication of the resulting information through statements, notes, and related explanations.
Can a profitable business run out of cash?
Yes. Profit and cash flow measure different things. Timing differences, unpaid invoices, inventory purchases, capital expenditure, loan repayments, and other commitments can affect cash even when the income statement reports a profit.
How often should a business prepare financial reports?
The appropriate frequency depends on the business’s needs and its legal or contractual obligations. Many businesses use monthly or quarterly internal reporting, while formal external reporting may follow an annual or other prescribed cycle.
The practical value of a clear financial record
Financial reporting matters because it turns scattered transactions into a coherent account of a business. It shows performance without reducing the business to profit alone, explains cash without ignoring longer-term obligations, and gives outside users a structured basis for evaluating decisions.
For a business, the value is cumulative. Accurate records support reliable reports; reliable reports support better analysis; and better analysis makes it easier to allocate resources, communicate with stakeholders, and respond to changing conditions. The result is not certainty, but a clearer starting point for responsible financial decisions.